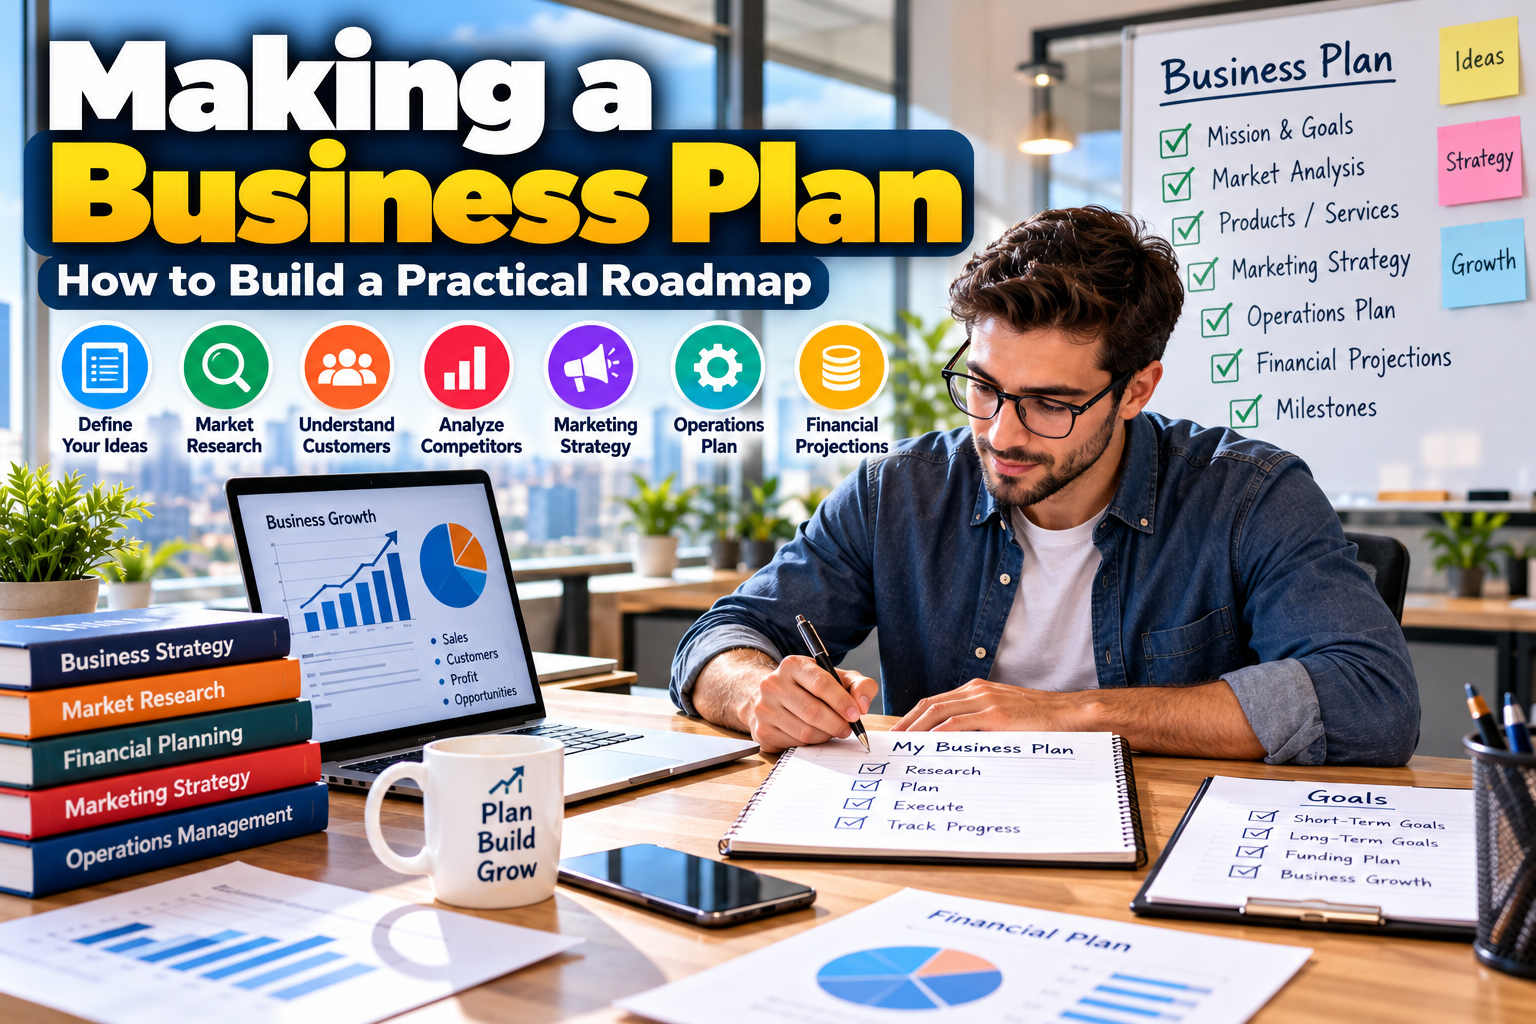
Making a business plan is an important step when starting a company, launching a new product, or preparing an existing business for growth. A clear plan helps you understand your customers, evaluate competitors, estimate costs, and decide how your business will generate revenue.
However, a business plan should be more than a document filled with goals and financial estimates. It should explain how your business will operate, what makes it valuable, and how you intend to turn your idea into a sustainable company.
Whether you are launching a small online business, opening a local store, or developing a startup, you can build a useful plan by following a structured process. This guide explains the essential sections, practical steps, and common mistakes to avoid.
What Is a Business Plan?
A business plan is a document that describes a company’s purpose, target customers, products or services, operating model, marketing approach, and financial expectations.
It acts as a roadmap for business decisions. It can also help you explain your idea to potential investors, lenders, business partners, and other stakeholders.
Most business plans follow one of two formats.
Traditional business plan: A detailed document that covers the business, market research, management, marketing, operations, and financial projections. Lenders and investors may request this format when evaluating a funding application.
Lean business plan: A shorter summary of the business model, target customers, value proposition, key activities, costs, and revenue streams. This format can work well when you want to test an idea and update your assumptions frequently.
The right format depends on your purpose. If you need external financing, check what the lender or investor expects before deciding how much detail to include.
Why Is Making a Business Plan Important?
A business plan helps you move from a general idea to a set of practical decisions. It does not guarantee success, but it can help you identify risks before committing significant resources.
1. Clarify Your Business Goals
Every business needs a clear direction. Without one, you may spend time on activities that do not support your main objectives.
A business plan helps you define what you want to achieve, who you want to serve, and how you will measure progress.
For example, an online retailer might aim to reach a specific monthly sales target within its first year. The plan can then identify the marketing, inventory, and customer service activities needed to pursue that target.
2. Understand Your Target Market
An attractive business idea is not enough if customers are unwilling to pay for it.
Market research helps you understand customer needs, purchasing behavior, market trends, and competing solutions. It can also reveal opportunities to differentiate your business.
Before investing heavily, take time to validate your business idea before investing your money. Early research can help you identify weaknesses, test demand, and refine your offer.
3. Make Better Financial Decisions
Starting and operating a business involves costs that are easy to underestimate. These may include equipment, inventory, software, employee wages, marketing, insurance, and professional services.
A business plan encourages you to estimate these expenses and compare them with expected revenue.
Financial projections can also help you determine how much starting capital you need, when cash shortages might occur, and what sales level may be required to cover costs.
4. Communicate Your Idea Clearly
Potential lenders, investors, and partners need to understand what your business does and why it has a realistic opportunity.
A well-organized plan explains the customer problem, your solution, the market opportunity, and the resources required to execute your strategy.
Clear assumptions and supporting evidence are more persuasive than unsupported claims about future success.
How to Create a Business Plan Step by Step
A practical business plan should answer several basic questions: What will your business offer? Who will buy it? How will you reach those customers? What will it cost to operate? How will the business make money?
Follow these steps to develop your plan.
Step 1: Write an Executive Summary
The executive summary provides a concise overview of the business and its main objectives. Although it appears first, writing it after the other sections can make it easier to summarize the complete plan accurately.
Include the following information:
- Your business name and purpose
- The product or service you offer
- Your target customers
- The problem your business solves
- Your competitive advantage
- Your main financial goals
- Your funding needs, if applicable
Keep the summary focused. A reader should understand the basic business concept without having to study every section.
For example, an online bookkeeping service might explain that it helps small businesses organize their financial records through monthly packages, secure digital tools, and personalized support.
Avoid making promises you cannot support. Use realistic targets and explain the assumptions behind them.
Step 2: Describe Your Business
This section explains what your company does, how it operates, and what makes it different from alternatives.
Start with your mission and the customer problem you intend to solve. Then describe your business model, proposed products or services, location, and ownership structure.
You should also explain your competitive advantage. This might involve specialized expertise, faster service, a distinctive product, convenient delivery, or a strong understanding of a particular customer group.
Consider these questions:
- What will the business sell?
- Who will benefit from the offer?
- How will customers receive the product or service?
- What makes the offer different?
- What resources are required to operate?
Your answers should describe a realistic business model rather than simply expressing your ambitions.
Step 3: Research Your Target Market
Market research helps you determine whether enough customers may be interested in your product or service.
Start by defining your ideal customer. Depending on your business, useful characteristics may include age range, location, industry, income level, buying habits, business size, or specific customer needs.
Next, investigate the market itself. Review industry reports, public data, customer surveys, interviews, online reviews, and relevant search trends.
For businesses targeting the United States, the U.S. Small Business Administration’s business planning resources provide guidance on market research, competitive analysis, and planning.
Try to answer these questions:
- Who is most likely to buy your product?
- What problem are they trying to solve?
- How do they currently solve it?
- What are they willing to pay?
- How large is your reachable market?
- What changes could affect demand?
Use evidence wherever possible. If you have not yet tested demand, label your assumptions clearly and plan a small experiment to gather better information.
Step 4: Analyze Your Competitors
Competitor research helps you understand the alternatives customers already have.
Identify direct competitors that sell similar products and indirect competitors that solve the same problem in another way.
Compare their pricing, product features, customer reviews, distribution methods, strengths, and weaknesses. Look for areas where your business could provide a better experience or serve an overlooked customer group.
For example, a local meal-preparation service might compete with restaurants, grocery delivery services, and ready-made meal subscriptions. Each alternative serves some of the same customer needs.
Your goal is not necessarily to offer the lowest price. You might compete through convenience, quality, specialization, customer support, or a more focused service.
Explain how your business will stand out and support that explanation with evidence.
Step 5: Explain Your Products or Services
Describe exactly what customers will receive and how your offer meets their needs.
Include the main features, benefits, pricing approach, delivery process, and any important suppliers or technology requirements.
If your business offers several products, explain which ones you plan to launch first. Starting with a focused selection can make it easier to manage costs and understand customer preferences.
You should also explain how your products or services may evolve. For example, you might introduce additional service packages after confirming demand for your initial offer.
If your business depends on intellectual property, proprietary technology, or specialized supplier relationships, describe how these assets support the business model.
Step 6: Develop a Marketing and Sales Strategy
Your business plan should explain how customers will discover your company and why they will choose your offer.
Start by identifying the channels that make sense for your audience. Depending on the business, these might include search engine optimization, paid advertising, social media, email marketing, partnerships, referrals, or direct sales.
Then outline the customer journey. Explain how a potential customer moves from discovering your business to making a purchase and, ideally, becoming a repeat customer.
Your marketing plan should identify:
- Primary customer segments
- Main marketing channels
- Pricing and promotional strategy
- Sales process
- Customer retention approach
- Marketing budget
- Performance metrics
Choose measurable indicators that connect to business goals. These might include qualified leads, conversion rates, customer acquisition costs, repeat purchases, and revenue generated by each channel.
Do not assume every marketing channel will work equally well. Begin with the most promising options, measure the results, and adjust your budget based on evidence.
Step 7: Outline Operations and Management
This section explains how the business will function from day to day.
Describe your main operating processes, staffing needs, suppliers, equipment, technology, and customer service arrangements.
If you will work alone initially, explain which responsibilities you will handle and which services you may outsource. If you plan to hire employees, outline the roles required and when you expect to add them.
Also describe the business structure and who will make important decisions.
For example, an online store may need reliable suppliers, inventory management, payment processing, order fulfillment, returns handling, and customer support.
Think about potential operational problems, too. Supplier delays, equipment failures, staff shortages, and software disruptions can affect performance. A basic contingency plan can help you prepare for these situations.
Step 8: Prepare Financial Projections
Financial planning helps you estimate whether your business model is financially workable.
Start by listing your startup costs. These may include registration, equipment, initial inventory, website development, deposits, professional fees, and launch marketing.
Next, estimate your ongoing costs, including rent, salaries, software subscriptions, supplies, insurance, and advertising.
Then prepare revenue projections based on reasonable assumptions about pricing, sales volume, and customer demand.
Your financial plan may include:
- Startup cost estimates
- Sales and revenue forecasts
- Profit and loss projections
- Cash flow projections
- Balance sheet estimates
- Break-even analysis
- Funding requirements, if applicable
A break-even calculation can help you understand how much you need to sell to cover your costs.
For a simple business selling one product, use this formula:
Break-even units = Fixed costs ÷ (Selling price per unit − Variable cost per unit)
Suppose your monthly fixed costs are $3,000. You sell a product for $50, and each unit costs $20 to produce and deliver.
Your contribution per unit is $30. Therefore:
$3,000 ÷ $30 = 100 units.
Under these assumptions, you would need to sell 100 units per month to cover the modeled costs. This example excludes additional complications such as taxes, financing costs, and changes in pricing or demand.
Prepare conservative, expected, and optimistic scenarios. This will help you understand how changes in sales or expenses could affect the business.
Step 9: Set Milestones and Review Your Plan
A business plan becomes more useful when it includes measurable actions and deadlines.
Instead of writing that you want to grow quickly, identify the specific steps required to reach your goal.
For example, your first six months might include:
| Time frame | Milestone |
|---|---|
| Month 1 | Complete market research and confirm the initial offer |
| Month 2 | Finalize pricing, suppliers, and startup budget |
| Month 3 | Launch the website or sales channel |
| Month 4 | Begin marketing and measure customer response |
| Month 5 | Review sales, costs, and customer feedback |
| Month 6 | Refine the offer and plan the next growth stage |
Adapt the timeline to your business. Some milestones will take longer than others, and that is normal.
Review your plan regularly. Update financial projections when actual results differ from expectations, and change your strategy when the evidence supports a different approach.
Business Plan Example for a Small Business
Imagine that Jordan wants to launch a small online store selling reusable household products.
Jordan begins by identifying environmentally conscious customers who want practical alternatives to disposable products. Market research suggests that these customers care about price, durability, convenience, and product quality.
The business plan then outlines a focused product range, a supplier strategy, an online sales channel, and a marketing approach based on useful content, search visibility, and customer referrals.
Next, Jordan estimates startup costs for initial inventory, website development, packaging, shipping materials, and marketing. The financial projections account for product costs, payment fees, shipping expenses, and ongoing software subscriptions.
Finally, Jordan sets milestones for launching the store, collecting customer feedback, measuring conversion rates, and reviewing cash flow.
This example demonstrates how the sections work together. Market research informs the product selection, the marketing plan supports sales, and the financial forecast tests whether the expected revenue can cover the costs.
The plan does not guarantee success. Instead, it gives Jordan a structured way to test assumptions and make better decisions as the business develops.
Common Business Planning Mistakes
A business plan is only useful when its assumptions are realistic and its information is relevant. Avoid these common mistakes when preparing yours.
Using Unrealistic Financial Estimates
Overestimating sales or underestimating expenses can create serious problems after launch.
Base your projections on market research, supplier quotes, pricing comparisons, and reasonable sales assumptions. If you lack reliable information, identify the uncertainty instead of presenting a guess as a fact.
Ignoring Competitors
Customers usually have alternatives, even if no business offers exactly the same product.
Research competing products and services so you understand customer expectations, pricing, and potential ways to differentiate your offer.
Setting Vague Goals
Goals such as increasing sales or becoming a leading brand do not provide enough guidance for daily decisions.
Set measurable targets and identify the actions needed to pursue them.
Underestimating Cash Flow Needs
A business can report sales and still struggle to pay its bills if customers pay late or expenses arrive before revenue.
Estimate when money will enter and leave the business. You can also learn how to manage business cash flow to prepare for payment delays and operating expenses.
Writing the Plan but Never Updating It
Market conditions, customer preferences, and operating costs can change.
Treat your business plan as a working document. Review actual performance, update assumptions, and revise the next steps when necessary.
Tips for Making a Business Plan More Effective
A strong business plan should be practical, easy to understand, and supported by credible information.
Keep it focused. Include details that help explain the business model, customer demand, operations, and financial outlook. Avoid lengthy sections that do not support a decision.
Use evidence. Support important assumptions with market research, customer feedback, supplier estimates, or actual business results.
Make the numbers consistent. Your sales forecast should align with your pricing, marketing strategy, operating capacity, and expected expenses.
Explain risks. Identify important challenges and describe how you might respond if they occur.
Match the format to your needs. A lean plan may be enough for testing an early idea. A lender or investor may require a more detailed document with supporting financial information.
Review progress regularly. Compare actual results with your plan and update the document as the business evolves.
Frequently Asked Questions
Q1: What Are the Main Parts of a Business Plan?
Ans: A traditional business plan commonly includes an executive summary, company description, market analysis, organization and management, products or services, marketing and sales strategy, funding request, financial projections, and supporting documents.
The exact structure can vary depending on your business and the purpose of the plan.
Q2: Can I Write a Business Plan Myself?
Ans: Yes. Many entrepreneurs prepare their own business plans using templates and reliable research. You may still want professional advice for complex financial forecasts, legal matters, tax questions, or funding applications.
Q3: How Long Should a Business Plan Be?
Ans: There is no universal length. A lean plan may fit on one page, while a detailed traditional plan can run for several pages or more. Focus on providing enough information for your intended readers and decisions.
Q4: Do Small Businesses Need a Business Plan?
Ans: A written plan can help small businesses understand customers, estimate costs, organize operations, and set priorities. It can also be useful when seeking financing or explaining the business to potential partners.
Q5: How Often Should I Update My Business Plan?
Ans: Review it regularly, such as quarterly, and whenever a major change affects your strategy, finances, customers, or operations. Established businesses may also compare actual results with projections each month.
Conclusion
Making a business plan helps you turn an idea into a structured approach to launching and managing a company. By defining your goals, researching customers, analyzing competitors, planning operations, and preparing financial projections, you can make decisions with greater clarity.
Start with the information you have, identify the assumptions that need testing, and improve the plan as you learn more.
Most importantly, use the document to guide real decisions. A practical business plan should help you understand what to do next, how much it may cost, and how you will measure progress as your business grows.
One thought on “Making a Business Plan: How to Build a Practical Roadmap”