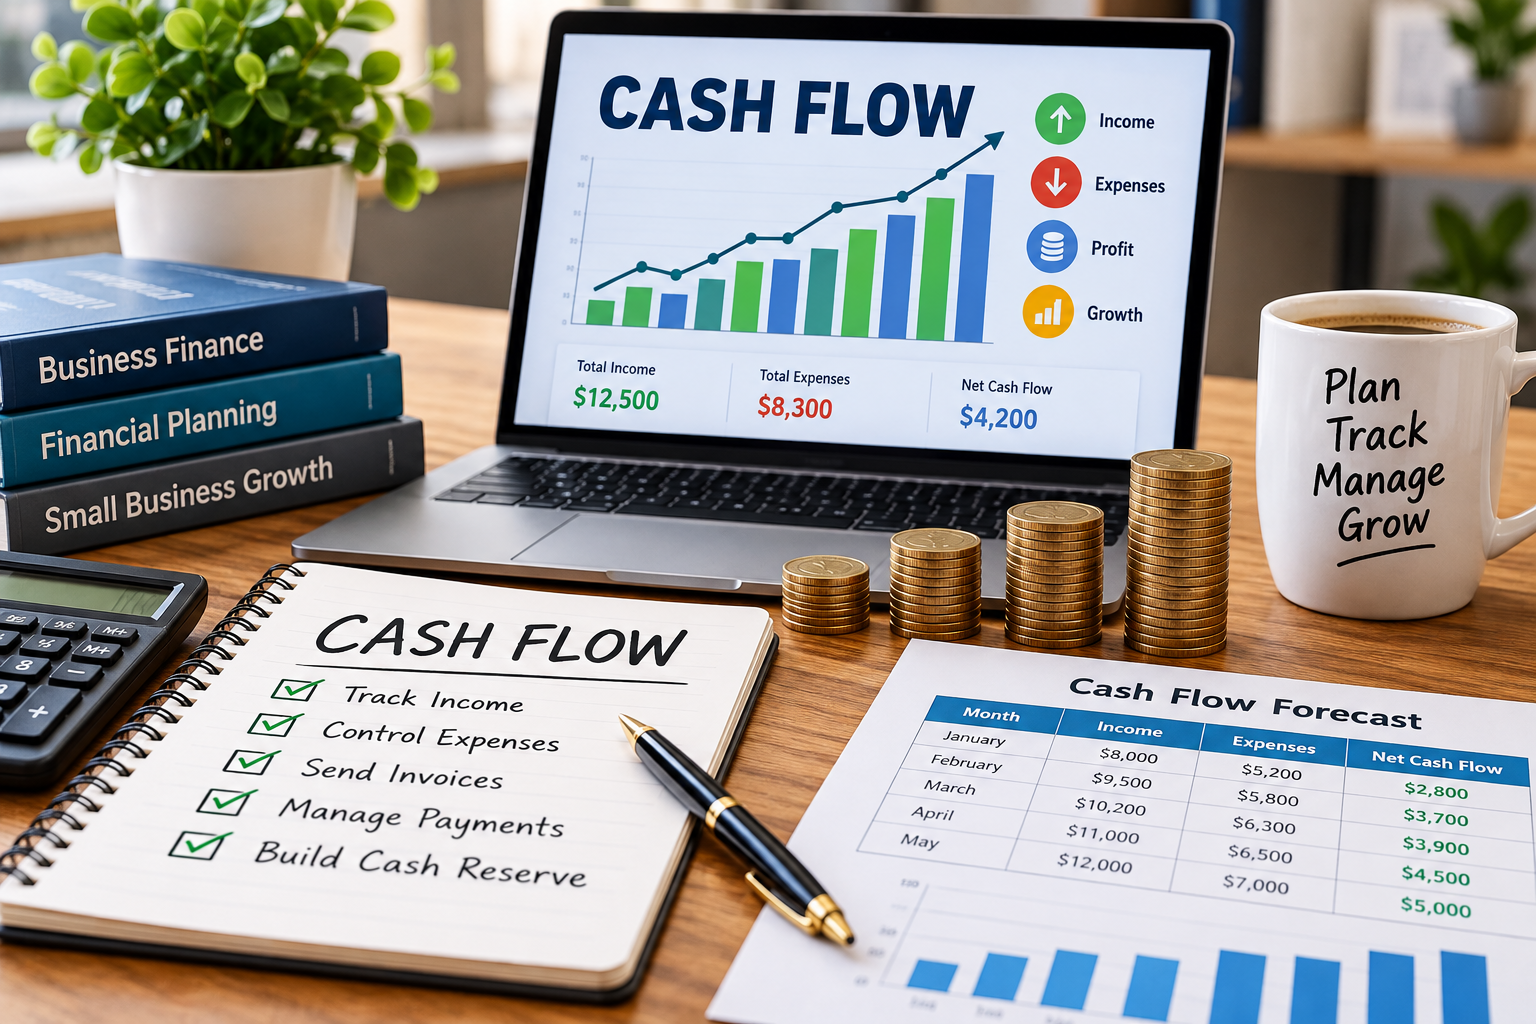
Running a business is not only about making sales. You also need to know when money is coming into the business, when bills must be paid, and how much cash will remain available.
This is why cash flow management is important. A business can have strong sales and still experience a cash shortage if customer payments arrive late or expenses need to be paid before revenue is collected.
The U.S. Small Business Administration highlights cash flow forecasting, accounts receivable, accounts payable, and identifying potential cash shortages as important parts of cash flow management.
The good news is that you do not need complicated financial systems to start. By tracking your money, forecasting upcoming income and expenses, and reviewing your finances regularly, you can make better day-to-day decisions.
What Is Business Cash Flow?
Business cash flow is the movement of money into and out of a business over a specific period.
Cash inflows are money coming into the business, such as:
- Customer payments
- Product sales
- Service income
- Business loans
- Other business income
Cash outflows are money leaving the business, such as:
- Rent
- Employee wages
- Supplier payments
- Software subscriptions
- Marketing costs
- Utilities
- Taxes
- Loan payments
Cash flow is different from profit. A business may record a sale but not receive the customer’s payment immediately. At the same time, the business may have bills that need to be paid now.
Understanding this timing difference helps business owners avoid relying on expected revenue that has not yet reached the bank account.
Why Is Cash Flow Important for a Business?
Cash flow helps a business meet its financial obligations while continuing normal operations.
Healthy cash flow can help you:
- Pay employees and suppliers on time
- Cover regular operating expenses
- Handle unexpected costs
- Plan future purchases
- Avoid unnecessary borrowing
- Prepare for slower sales periods
- Make informed business decisions
The SBA notes that cash flow is a critical factor for businesses and recommends forecasting sales, costs, expenses, and cash flow, then comparing actual results with expectations.
1. Track Your Cash Inflows
The first step in managing cash flow is knowing where your money comes from.
Record all expected and received income, including:
- Customer invoices
- Online sales
- Service payments
- Recurring revenue
- Other business income
Do not only look at total sales. Pay attention to when the money is actually received.
For example, suppose your business makes $10,000 in sales during a month, but customers have 30-day payment terms. You may not receive all of that money during the same month.
Keeping accurate records makes it easier to understand your actual financial position. The IRS recommends maintaining records that clearly show business income and expenses.
2. Track Your Cash Outflows
After tracking income, record where your business money is going.
Common expenses include:
- Rent
- Payroll
- Supplier invoices
- Advertising
- Software
- Insurance
- Utilities
- Transportation
- Professional services
- Taxes
- Loan payments
Separate your expenses into categories so you can identify which costs are essential and which may be reduced.
A regular review can reveal subscriptions you no longer need, unnecessary purchases, or expenses that have increased without providing enough value.
3. Create a Cash Flow Forecast
A cash flow forecast estimates how much money you expect to receive and spend during a future period.
Start by listing:
- Expected customer payments
- Other expected income
- Regular business expenses
- Upcoming supplier payments
- Payroll and other major costs
- Loan or financing payments
- Expected remaining cash
Using cash flow projections can help you identify potential shortages before they become serious problems. The SBA recommends comparing forecasts with actual results and making adjustments when results differ from expectations.
Simple Cash Flow Forecast
| Cash Flow Item | Expected Amount |
|---|---|
| Customer Payments | $8,000 |
| Operating Expenses | $4,500 |
| Supplier Payments | $1,500 |
| Other Costs | $500 |
| Expected Remaining Cash | $1,500 |
These figures are examples only. Actual amounts will depend on your business.
A forecast does not need to predict the future perfectly. Its purpose is to give you a clearer picture of upcoming cash movements so you can plan ahead.
4. Send Invoices on Time
Late invoicing can delay payments and create unnecessary pressure on your cash flow.
If you provide products or services on credit, create a consistent invoicing process.
Consider:
- Sending invoices as soon as work is completed
- Clearly showing the amount due
- Including payment instructions
- Stating payment terms
- Checking invoices for errors
- Following up when payments become overdue
The faster you invoice accurately, the sooner customers have an opportunity to pay.
5. Improve Your Accounts Receivable
Accounts receivable represents money customers owe your business.
If unpaid invoices continue to increase, your sales may look strong while the amount of cash available remains limited.
To improve collections:
- Monitor unpaid invoices regularly
- Follow up on overdue payments
- Make payment methods convenient
- Confirm payment terms before starting work
- Consider deposits for appropriate projects
- Keep customer billing information accurate
A simple accounts receivable report can show which invoices are current and which require follow-up.
6. Control Unnecessary Expenses
Reducing unnecessary spending can help preserve available cash.
Review expenses such as:
- Unused software subscriptions
- Unnecessary memberships
- Excessive advertising costs
- Office expenses
- Unplanned purchases
- Services that are no longer needed
This does not mean cutting every expense. Instead, evaluate whether each cost supports an important business objective.
For example, removing a software subscription that nobody uses may save money without affecting operations.
7. Manage Inventory Carefully
Inventory can also affect cash flow.
When you purchase products, money leaves the business before those products are sold. If inventory remains unsold for a long period, your cash may be tied up.
To manage inventory more effectively:
- Track which products sell quickly
- Identify slow-moving products
- Avoid unnecessary overstocking
- Review sales trends before large purchases
- Coordinate inventory purchases with expected demand
Businesses that sell physical products should pay particular attention to the relationship between inventory purchases and customer sales.
8. Build a Cash Reserve
A cash reserve can give your business more flexibility when unexpected costs or temporary slowdowns occur.
You might use a reserve for situations such as:
- Emergency repairs
- Unexpected operating costs
- Temporary sales declines
- Equipment replacement
- Urgent supplier payments
There is no single reserve amount that works for every business. Your target should reflect your operating costs, revenue stability, industry, and financial responsibilities.
Start with a realistic amount and increase it gradually as your business becomes more stable.
9. Separate Business and Personal Finances
Keeping business and personal finances separate makes financial tracking easier.
Use a dedicated business bank account for business transactions whenever appropriate. This can help you clearly identify business income and expenses.
The IRS specifically recommends keeping business and personal accounts separate and explains that good records help businesses monitor progress, prepare financial statements, and track income and expenses.
If you are creating or improving a business plan, financial information such as expected revenue, expenses, and cash requirements can also help you make more realistic decisions about your business.
10. Review Cash Flow Regularly
Cash flow management should not be something you check only when money becomes tight.
Create a regular review routine.
For example:
Weekly:
- Check your current bank balance
- Review incoming payments
- Check overdue invoices
- Review upcoming major expenses
Monthly:
- Compare actual income with expectations
- Review expenses
- Update your forecast
- Check your cash reserve
- Identify potential problems
The SBA recommends reviewing actual results against forecasts so business owners can identify differences and make adjustments.
Common Cash Flow Mistakes to Avoid
Even a growing business can experience cash flow problems when financial information is not reviewed carefully.
Common mistakes include:
Ignoring Unpaid Invoices
Sales do not automatically mean cash is available. Monitor unpaid invoices and follow up appropriately.
Spending Based Only on Expected Revenue
Do not treat money you expect to receive as money already available.
Failing to Forecast Future Expenses
Large upcoming payments can create problems if you do not plan for them in advance.
Mixing Personal and Business Money
Combining accounts can make it harder to understand actual business performance and maintain accurate records.
Holding Too Much Inventory
Excess inventory can tie up cash that could otherwise be used for operating expenses or other business needs.
Not Keeping a Cash Reserve
Without some available cash, an unexpected expense can put pressure on daily operations.
Business Cash Flow Checklist
Use this checklist to keep your finances organized:
- Track all business income
- Record business expenses regularly
- Monitor unpaid invoices
- Create a cash flow forecast
- Review upcoming payments
- Control unnecessary expenses
- Manage inventory carefully
- Keep business and personal finances separate
- Build a cash reserve
- Review cash flow regularly
- Compare actual results with forecasts
- Adjust spending when necessary
FAQs
Q1: What is cash flow in a business?
Ans: Cash flow is the movement of money into and out of a business. It includes customer payments, sales, operating expenses, supplier payments, payroll, and other financial transactions.
Q2: Why is cash flow important?
Ans: Cash flow helps a business pay its regular expenses, manage unexpected costs, and plan for future financial needs.
Q3: How can a small business improve cash flow?
Ans: A business can improve cash flow by collecting payments faster, controlling unnecessary expenses, managing inventory, forecasting future cash needs, and maintaining a cash reserve.
Q4: How often should I review cash flow?
Ans: Many businesses benefit from checking cash movements regularly and performing a more detailed financial review at least monthly.
Q5: What is the difference between cash flow and profit?
Ans: Profit generally compares revenue with expenses, while cash flow focuses on when money actually enters and leaves the business. A business can report profit while still experiencing a temporary cash shortage.
Final Thoughts
Managing business cash flow is an ongoing process. You do not need to predict every financial event perfectly. Instead, focus on understanding your current cash position and preparing for what is coming next.
Track income and expenses, send invoices promptly, monitor unpaid payments, control unnecessary costs, and create a realistic cash flow forecast.
It is also important to keep business and personal finances separate and maintain organized records. The IRS notes that good records help business owners monitor their businesses and prepare accurate financial statements.
With consistent financial reviews and better planning, you can identify potential cash shortages earlier and make more informed decisions about your business.
One thought on “How to Manage Business Cash Flow: A Simple Guide”